
A Winnipeg employer can consider an HSA as a defined medical reimbursement benefit. It is not a personal savings account funded with unrestricted pre-tax payroll contributions. Participant, medical-expense and plan requirements must be checked before reimbursement.
Confirm the Employer and Participants
Favourable federal treatment depends on a qualifying Private Health Services Plan (PHSP) and its actual operation. For an incorporated owner, the benefit must arise in an employee capacity rather than solely as a shareholder.
CRA’s archived warning addresses the HSA arrangement described for a sole proprietor without arm’s-length employees. Qualifying self-employed PHSP premiums have separate contract, income, employee and deduction-limit conditions. Incorporation alone does not establish every benefit, and not every employee plan requires the employer to be incorporated.
Family coverage depends on actual PHSP covered-person, related-household and plan conditions. A profession or family relationship alone does not establish unrestricted household coverage.
Allowances, Funding and Tax Treatment
Document reasonable employment-based allowances, covered categories, periods and deadlines. There is no single universal CRA dollar allowance for every employer HSA. An allowance is a benefit limit; it is not automatically an incurred deduction or a personally owned investment balance.
Qualifying employee PHSP benefits are generally non-taxable federally; Québec has separate provincial rules where applicable. Employer deductions depend on qualifying costs, employment purpose, reasonableness and the actual business facts. Assess any employee payments, fees, taxes and reporting separately.
The federal framework does not establish that every provincial tax, payroll, privacy or employment obligation disappears. Apply requirements relevant to the actual Manitoba employer and transaction.
Medical Expenses and Patient Travel
Potential categories include eligible dental treatment, prescription eyewear, qualifying drugs, recognized-practitioner services and specified devices. Check the actual service jurisdiction and any required prescription, certification or other evidence. A general health purpose or receipt alone is insufficient.
Under the usual drug rule, the medicine must legally require a prescription and the purchase must be recorded by a pharmacist. Specific exceptions have their own requirements. Gym memberships and ordinary vitamins or supplements are ineligible medical expenses even if prescribed, except B12 therapy prescribed for pernicious anaemia.
A trip to Winnipeg for care is not automatically eligible. CRA’s medical-travel conditions include substantially equivalent care being unavailable nearer home, a reasonably direct route and travel that is reasonable in the circumstances.
Qualifying transportation may be considered at 40 km or more one way; meals, lodging and parking generally require at least 80 km and the other conditions. Vehicle expenses and an attendant have additional requirements. Keep the service, route, distance and expense evidence.
A Hypothetical $1,200 Dental Example
Assume a qualifying employer plan reimburses $1,200 of eligible dental expenses for a covered person. At an assumed 10% administration rate, administration is $120 and funding totals $1,320 before applicable taxes and separate charges.
The $1,200 is an illustrative input, not a Winnipeg family-spending average or customer invoice. It establishes no guaranteed tax saving. Obtain an actual treatment quote and compare the employer’s and employee’s tax facts and complete charges.
Compare Actual Coverage and Costs
Use dated local quotes and the remaining expense after other-plan reimbursement. Unsupported Winnipeg/national price tables, testimonials and forecasts do not establish the actual cost of a proposed plan.
Qualifying insured PHSP benefits can also receive favourable federal treatment. Compare insurance premiums, benefits, limits, deductibles, exclusions and high-cost risks. A defined HSA allowance does not guarantee every bill or automatically outperform insurance.
Setup and Claims Administration
- Confirm the employer, eligible participants and qualifying arrangement.
- Document reasonable allowances, categories, periods and deadlines.
- Submit itemized receipts, category-specific evidence and other-plan reimbursement details.
- Follow agreed review, employer-funding and payment terms.
- Retain plan, claim and payment records and apply actual reporting requirements.
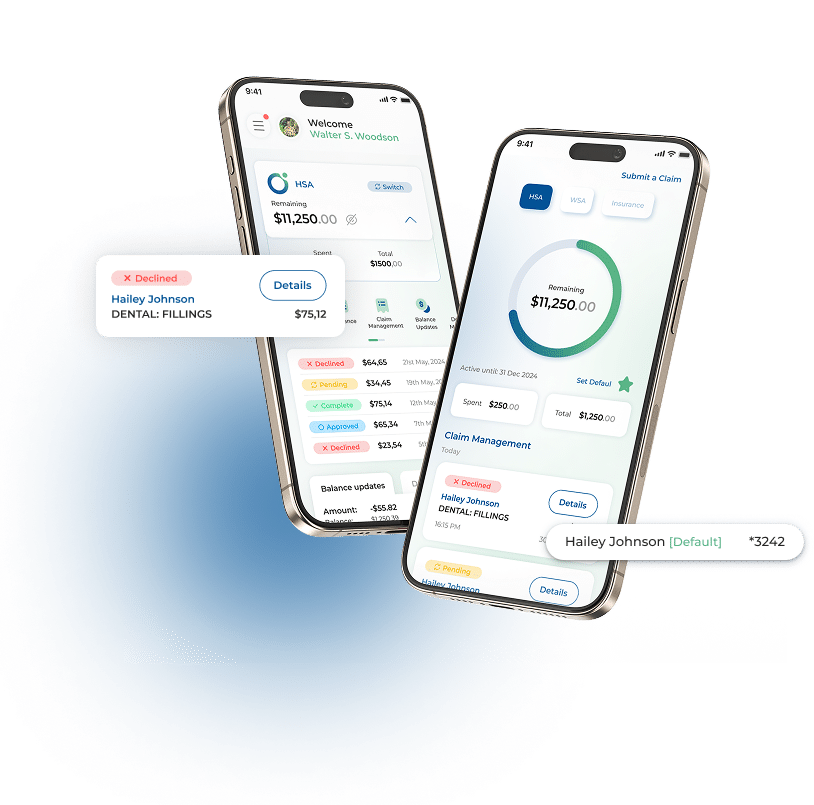
Under Wellbytes’ current HSA Pay-as-You-Use terms, administration is 10% of eligible reimbursed amounts plus applicable taxes, with no setup or recurring subscription fee. Other arrangements follow their accepted terms. Confirm actual digital and support functions; no provider guarantees instant claim decisions, automatic payment or audit protection.
Review Wellbytes’ current terms or ask about a Winnipeg employer’s proposed medical benefit.
Sources checked October 21, 2026: CRA: medical benefits and PHSP treatment; CRA: eligible medical expenses and item conditions; CRA: recognized medical practitioners by jurisdiction; CRA: business expenses and self-employed PHSP premiums; CRA: warning about personal self-insured HSAs; Income Tax Act, section 15: shareholder benefits; Income Tax Act, section 67: reasonable expenses; Wellbytes: administration, funding and fee terms; CRA: recordkeeping and retention requirements.



